FEE-ONLY · ADVICE-ONLY · NO AUM
Is Your Financial Plan on Track?
You have managed your own money and done well at it. But every so often a decision comes along big enough that you want a real expert to look over your shoulder and tell you what you might be missing. That is what I do. Straight answers on the decisions that matter, priced for the decision rather than the size of your portfolio, from someone whose only job is to give you good advice.
WHAT I HELP WITH
A Real Expert to Look Over Your Shoulder at the Decisions That Matter
People usually come to me when a decision gets large enough that doing it alone no longer feels wise. Getting serious about retirement, at any stage from just beginning to the final approach. Approaching the college affordability question without derailing your own plan. Or simply wanting a knowledgeable second read on a plan you have built yourself. These are the moments when money is in motion and the stakes just got real. I help you think the decision through before you commit, not after.
Reach Real Expertise Without a Portfolio Minimum
You do not need a large portfolio to get a competent, unbiased read on your decision. Advice-only pricing means the expertise is the product, available when you actually need it.
Get an Unbiased Second Opinion
Already managing your own investments and decisions? I will stress-test your plan and tell you what is working, what is missing, and what to fix. I will not try to take it over.
Work Through It
Together
Every engagement is built with you, not delivered to you. You leave understanding not just what to do, but why it is right for your situation.
THE REAL COST OF GETTING IT WRONG
You want to be in control of your financial future. Major transitions can make that hard to hold onto.
Life's transitions can test your knowledge and confidence.
Every advisor you've talked to seems to want something: your assets, your trust, or a fee structure that damages your ability to grow your wealth.
You feel best when you are the one making these calls. You're just not always sure you have everything you need to make them well.
You're making decisions you've never had to make before, and there's no real playbook for getting them right.
The stakes are real. Most of these decisions can be undone if you get them wrong, but rarely without real cost.
“
I was quoted a fee of 1% of my entire portfolio, every year, indefinitely, just to have someone look at it. I found that absurd.
Chris Noble, on the moment that led him to build a different kind of advisory practice. More on that below.
WHY CHOOSE GREYDOG FINANCIAL?
Decisions, Not Just Recommendations
Decisions, Not Just Recommendations
Most financial advice arrives as a conclusion. You're told what to do, not why it makes sense for you specifically. I work differently. I lay out the real trade-offs (the actual costs, risks, and alternatives) and walk through them with you before any decision gets made.
This isn't because I don't have a view. It's because the decision is yours, and you should understand every part of it.
Right-Sized to the Decision
You get just enough expertise to resolve the decision in front of you, scoped to the moment that brought you in. No permanent retainer, no overhead you do not need, no fee that grows simply because your balance does.
You leave with a decision you understand and can act on with confidence.
No AUM, No Conflicts of Interest
I don't manage assets, and I don't get paid more when you do certain things with your money. There's no incentive working against you in the background.
What that means in practice: the advice you get is the advice that's actually right for you, not the advice that's right for my fee structure.
A Quieter Understanding of How Decisions Get Made
Many financial decisions are shaped less by the math than by stress, timing, or old beliefs about money. Graduate training in financial psychology helps me notice when that is happening and frame the question well. It stays in the background, informing the work rather than becoming a lecture about it.
The result is advice that fits the decision in front of you, and holds up after the conversation ends.
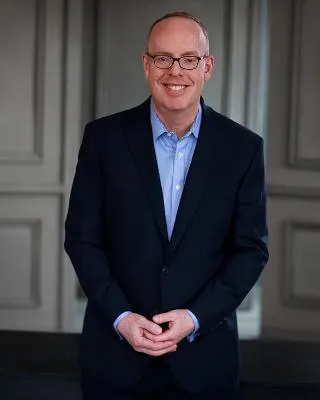
Chris Noble, Founder
HI THERE, I'M CHRIS
A different way into this work
For most people, big financial decisions arrive at the worst possible time. You're navigating a transition, short on bandwidth, and being asked to make calls that will shape years of your life with information you didn't ask to need.
I came to this work from a different angle. I started my career with an MBA from the University of Michigan's Ross School of Business, then spent nearly thirty years in corporate marketing. Personal finance was something I pursued on the side that whole time, not as a job, but as a real interest. Over time, that interest became a hobby, and the hobby became a genuine passion: researching, building our family's investment and wealth-building strategy, refining how I made decisions with our money.
At one point, with our plan already in place, I wanted what anyone careful would want: a second opinion. I found an advisor to review what I'd built. I was quoted a fee of 1% of my entire portfolio, every year, indefinitely, just to have someone look at it. I found that absurd. Why should a second opinion cost a percentage of everything I own, for as long as I own it?
That moment crystallized something I'd been circling for years. Real expertise is gated behind assets. A careful person with a good plan and a single question had no clean place to turn that did not come attached to a percentage of everything they own.
Years of careful planning and discipline, shared with my wife, meant that when the moment came, we were in a position where I could actually pursue this as a second career. So I went back to school, completing a master's degree in financial planning and financial psychology at Creighton University, a credential that complements the MBA I earned at the start of my career. There, I studied under some of the field's leading researchers on the psychology behind financial decisions. What I learned confirmed what I already suspected: most financial mistakes aren't math mistakes. They're decisions shaped by stress, identity, and beliefs about money that never get examined.
That's the foundation Greydog Financial is built on. Not asset management. Not a fee that grows simply because your balance does. Trusted expertise, made accessible when the decisions matter, priced for the decision rather than the size of your portfolio.
You don't have to make these decisions alone. You also don't have to hand them over completely.
Credentials built for judgment, not sales. A fee model built to remove conflicts of interest.
MBA, Ross School of Business, University of Michigan
Foundational training in strategy and decision-making, the same discipline applied here to financial decisions.
Master's in Financial Planning and Financial Psychology, Creighton University
Studied under some of the field's leading researchers on the psychology behind financial decisions, the basis for understanding not just what to decide, but why people struggle to.
Fee-Only, Advice-Only, No AUM, No Custody
By structure, not just by claim. There's no fee that grows simply because your balance does, and no incentive to manage assets rather than advise on them.
In addition to the training, I've made a major transition myself: leaving a thirty-year corporate career to build something new, later in life, on purpose. I understand what it takes to make a decision like that carefully, and to live with it afterward.
The fee structure here is a direct response to the one I was quoted for a single second opinion. It's the reason this firm doesn't bill against your assets.
THE PLAN
Choose How We Work Together
Every engagement is a flat fee, quoted before any work begins. No percentage of your assets, no commissions, and no fee that grows because your balance does.
PROJECT WORK
The Single Decision
For people who don't need the full plan, just clarity on one specific, high-stakes decision. I scope the question, work through the options and trade-offs, and look at how the decision ripples into the rest of your financial life, since few decisions are really as isolated as they first appear. You walk away with a decision made and a strategy to execute it: not a binder of advice you have to translate into action yourself.
Flat fee, quoted upfront. Projects start at $500. Scoped once we define the question, so you know the full cost before we begin. Hourly work fits here too, with a two-hour minimum.
ON-TRACK ASSESSMENTS
Where Do I Stand?
For people who want a straight answer to one question before anything deeper: am I on track, and what am I missing? I gather the full picture, model it, and give you a clear read on where you stand, with the largest drivers named and the dependencies your situation touches surfaced. A diagnosis, not a sales step.
Retirement On-Track Assessment, $1,497. College Savings On-Track Assessment, $297. If you move on to a full plan, the assessment is credited toward it, so you reach the same place either way.
PLANNING ENGAGEMENT
The Complete Picture
For people who want the complete picture, not just one decision answered in isolation. This is a comprehensive financial plan covering cash flow, investing, tax strategy, and retirement, built together so every piece connects to the others. It's often triggered by a major transition, but not always. It's also the right fit if you've built your own approach over the years and want a thorough second opinion: a real stress test of the whole plan, not just a quick gut check.
$3,497 flat. Paid in stages as the work is done, with no percentage of your assets. We build the plan together, and I show the thinking and the rationale at every step, so you see why each piece is where it is. We fine-tune it to your liking as we go. You don't leave with a plan I made for you. You leave owning one you understand.
Retirement: is your plan actually on track?
College: approaching affordability without derailing retirement
Second opinion for those managing their own plan: “What am I missing?”
RETIREMENT
Is your retirement actually on track, at any stage of planning
Pension decision: lump sum vs. annuity
Social Security claiming strategy
Roth conversion: does it make sense, and when
Withdrawal sequencing: the shift from saving to spending it down
Insurance audit: making sure coverage actually matches your risk
COLLEGE AFFORDABILITY
“Is our college savings on track?”
“What types of schools can we afford?”
How to approach the affordability and fit decision with clear eyes
Funding college without derailing your own retirement
529-to-Roth rollover (SECURE 2.0)
THE SECOND OPINION
“What am I missing?” a clean read on a plan you have built yourself
Reviewing and stress-testing a self-managed portfolio
Developing a personal investment philosophy and strategy
Employer stock concentration: when and how to diversify
Stock option / RSU exercise strategy
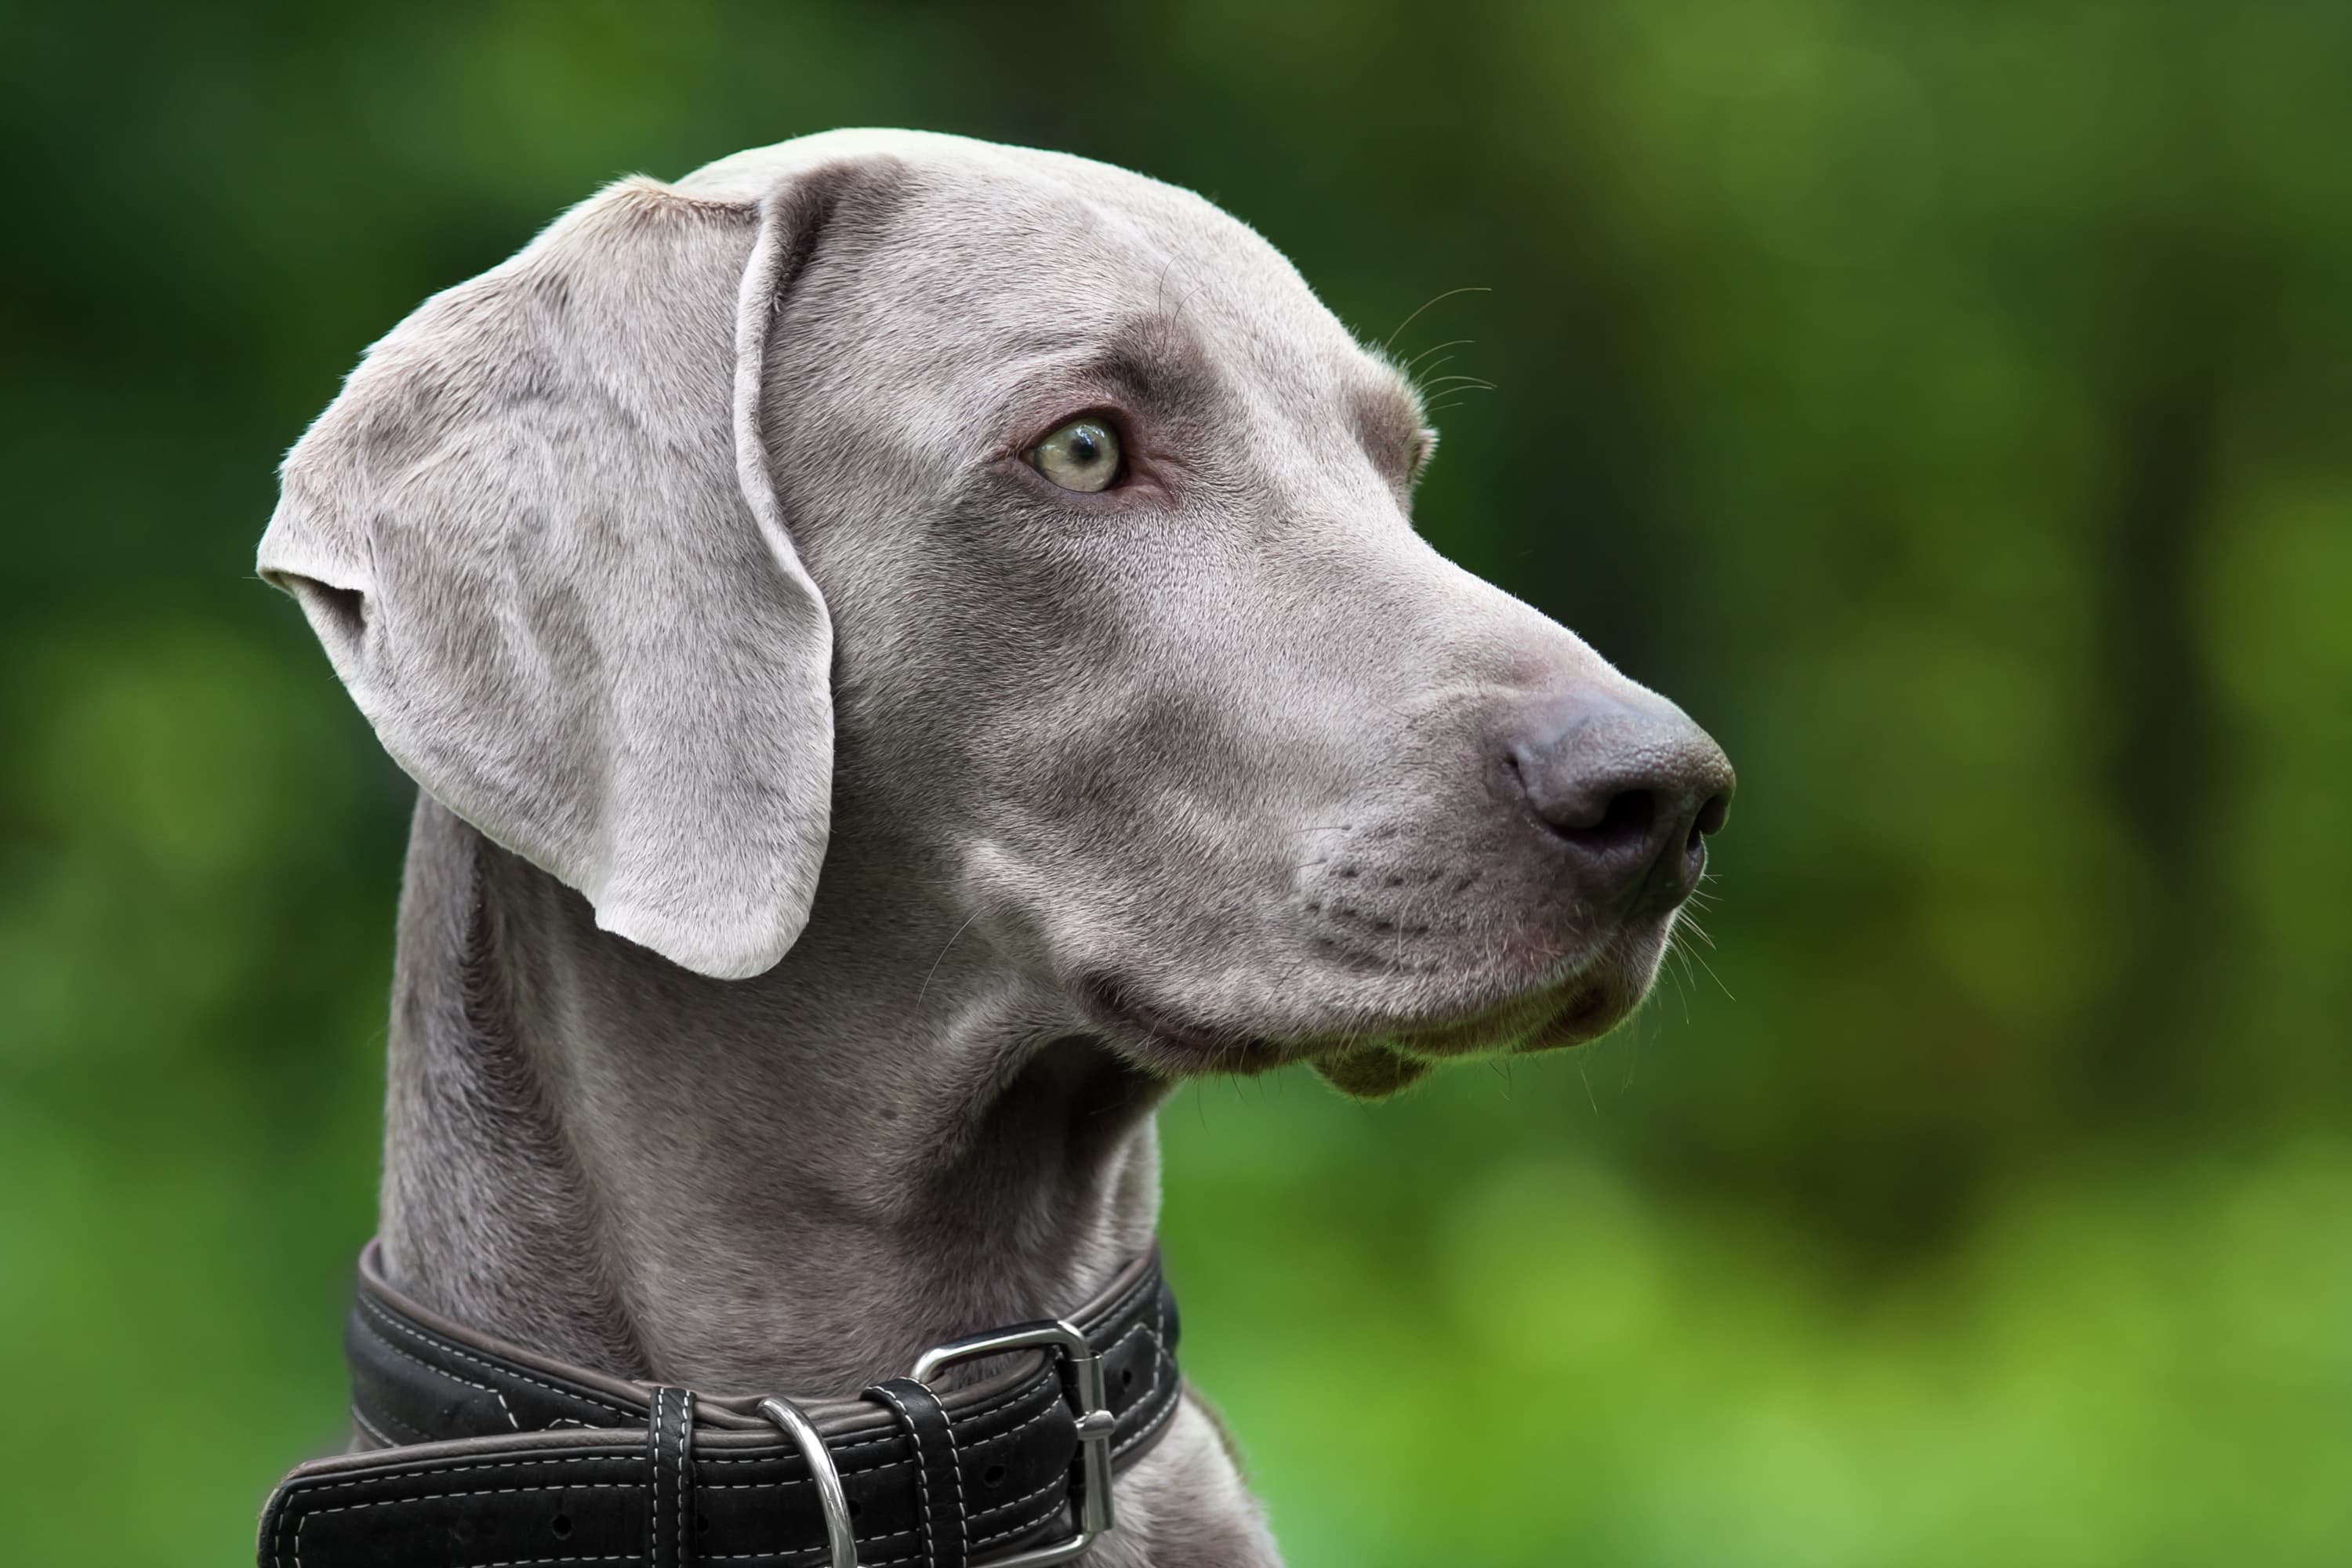
WHY "GREYDOG"?
The Grey Ghost
People often ask about the name. It traces back to the Weimaraner, the breed sometimes nicknamed "the grey ghost." I've shared my home with several over the years, including my current companion, Rocky. They've never been flashy dogs. They're steady, loyal, and quietly present for the long haul.
That's the same standard I hold myself to here: no flash, no pressure, just steady presence through decisions that matter, for as long as you need it.
IN PLAIN TERMS
What Greydog Financial Actually Is
There is a particular kind of person the financial industry serves badly: the one who has taken the time to understand their own money and manage it well. You have done the reading, built a plan, and stayed disciplined. And then a decision arrives that is big enough, or irreversible enough, that you want a real expert to confirm you are not about to miss something. At that exact moment, most of the advice available to you comes from people who benefit more from your uncertainty than your clarity, and who want to manage your money rather than answer your question.
That's not a cynical take. It's how the traditional advisory model is actually built. Most financial advisors are paid a percentage of the assets they manage, year after year, whether or not their advice that year was worth the fee. And if your portfolio isn't large enough to be worth managing, you often can't get good advice at all. Real expertise ends up gated behind assets, out of reach for the people who most need a clear read on a decision.
I learned that firsthand, not as an advisor, but as a prospective client. After years of building my own investment approach, I wanted a second opinion. I was quoted a fee of one percent of my entire portfolio, every year, indefinitely, just to have someone review what I'd already built. I found that absurd, and that moment crystallized something I'd been circling for a while: there had to be a better way to get good financial guidance, priced for the decision in front of you rather than the size of your portfolio.
So I built one. Greydog Financial is fee-only and advice-only. No assets under management, no custody, no products, and no fee that grows simply because your balance does. I bring an MBA from the University of Michigan's Ross School of Business and a master's degree in financial planning and financial psychology from Creighton University, where I studied under some of the field's leading researchers on the psychology behind financial decisions. Many financial decisions, I learned, are shaped as much by stress, identity, and old beliefs about money as by the math. That training stays in the background of the work, helping me frame a question well without turning the conversation into a lecture.
It is not only about the structure, though. This is a second career, and at this stage the work is as much about helping people and passing on what I know as it is about the business. That is the real reason there are no minimums. I want to be useful to someone just starting to build wealth as much as to someone approaching retirement. The decisions matter just as much at the beginning, and those are often the people no percentage-based advisor will take.
In practice, that work takes one of a few shapes. A comprehensive Planning Engagement, for people who want the complete picture across cash flow, investing, taxes, and retirement. Project Work, for people who need clarity on one specific decision, like approaching the college affordability question, evaluating a pension choice, or modeling what a divorce settlement means for your financial future (the legal terms themselves are between you and your attorney). Or, for many people, an On-Track Assessment first: a straight read on where you stand before deciding whether you need anything deeper, credited toward the full plan if you go on to build one.
None of this requires you to hand your financial life over to someone else to manage. You get a straight answer and the reasoning behind it from someone whose only incentive is a good outcome for you.
Trusted expertise, made accessible when the decisions matter, without handing your financial life over to get it.
LET'S TALK
You don't have to make these decisions alone. You also don't have to hand them over completely.
Start with a conversation. We'll figure out together whether an on-track assessment, a single project, or a full planning engagement is the right fit for where you are right now. Reach me directly at [email protected].
Fee-only, advice-only financial guidance. Trusted expertise, accessible when the decisions matter.
PRACTICE
© 2026 Greydog Financial. All rights reserved.
Christopher Noble LLC dba Greydog Financial is a registered investment adviser in the State of Michigan. Registration as an investment adviser does not imply a certain level of skill or training.